How to Save Money Every Month on a Low Salary
Introduction
Saving money can be challenging when income is limited and everyday expenses continue to rise.
However, even small, consistent savings can support financial stability. The key is to understand your spending habits and create a realistic plan.
Step 1: Track Monthly Income
Begin by calculating your take-home income.
Include regular salary and other reliable sources of income. Avoid budgeting around uncertain earnings.
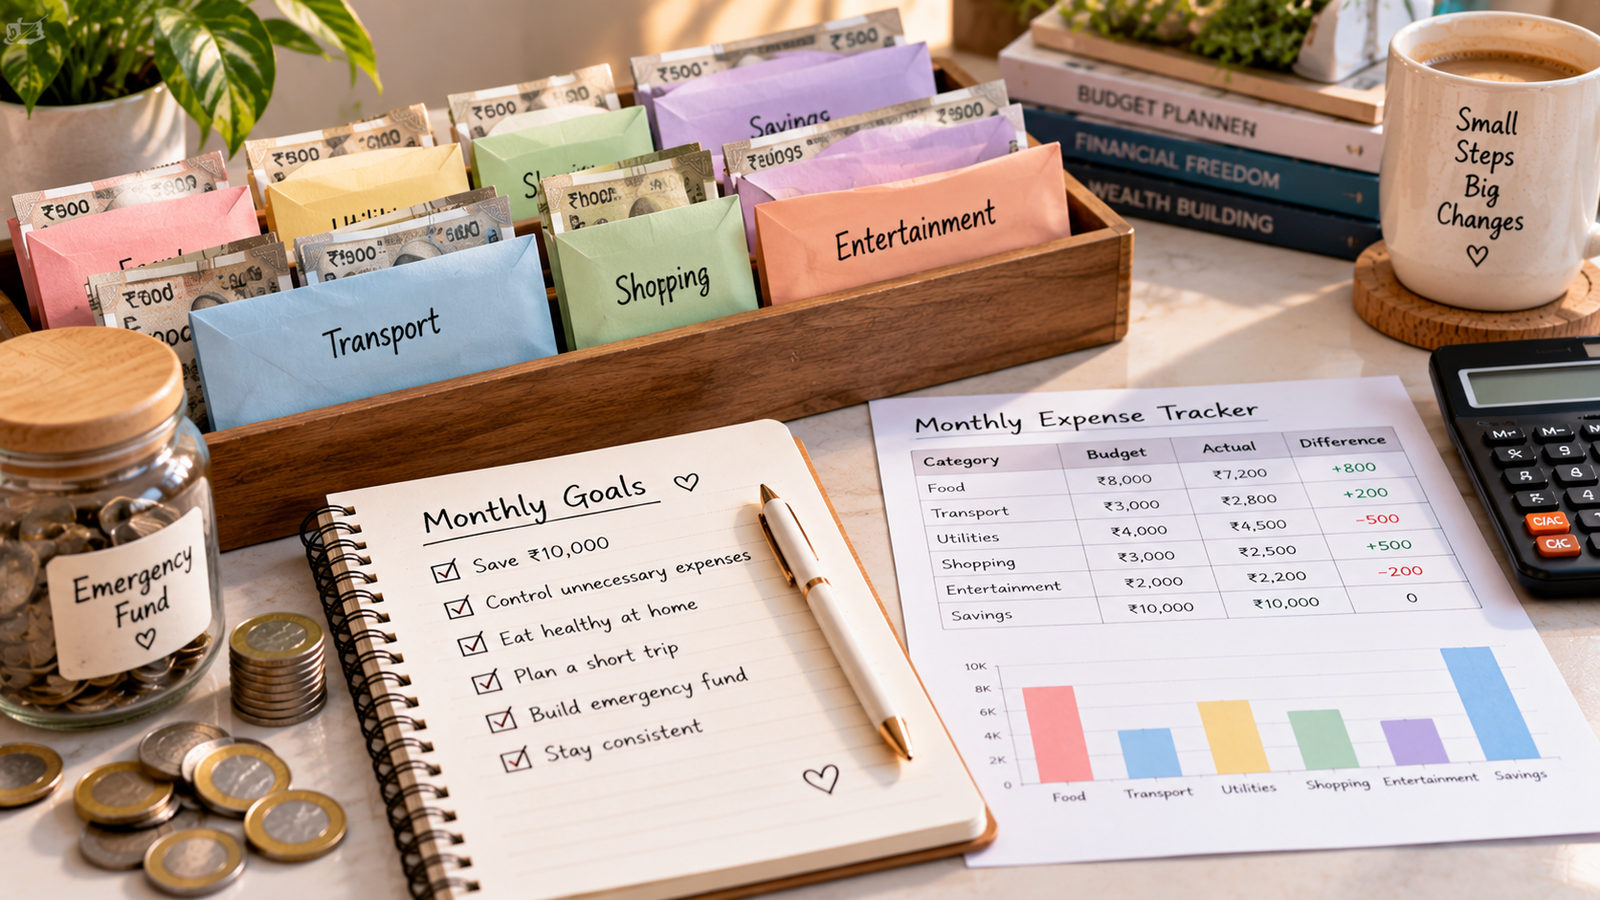
Step 2: Record Your Expenses
Divide your expenses into categories such as housing, groceries, transportation, utilities, debt repayments, and discretionary spending.
Use a notebook or spreadsheet to track them.
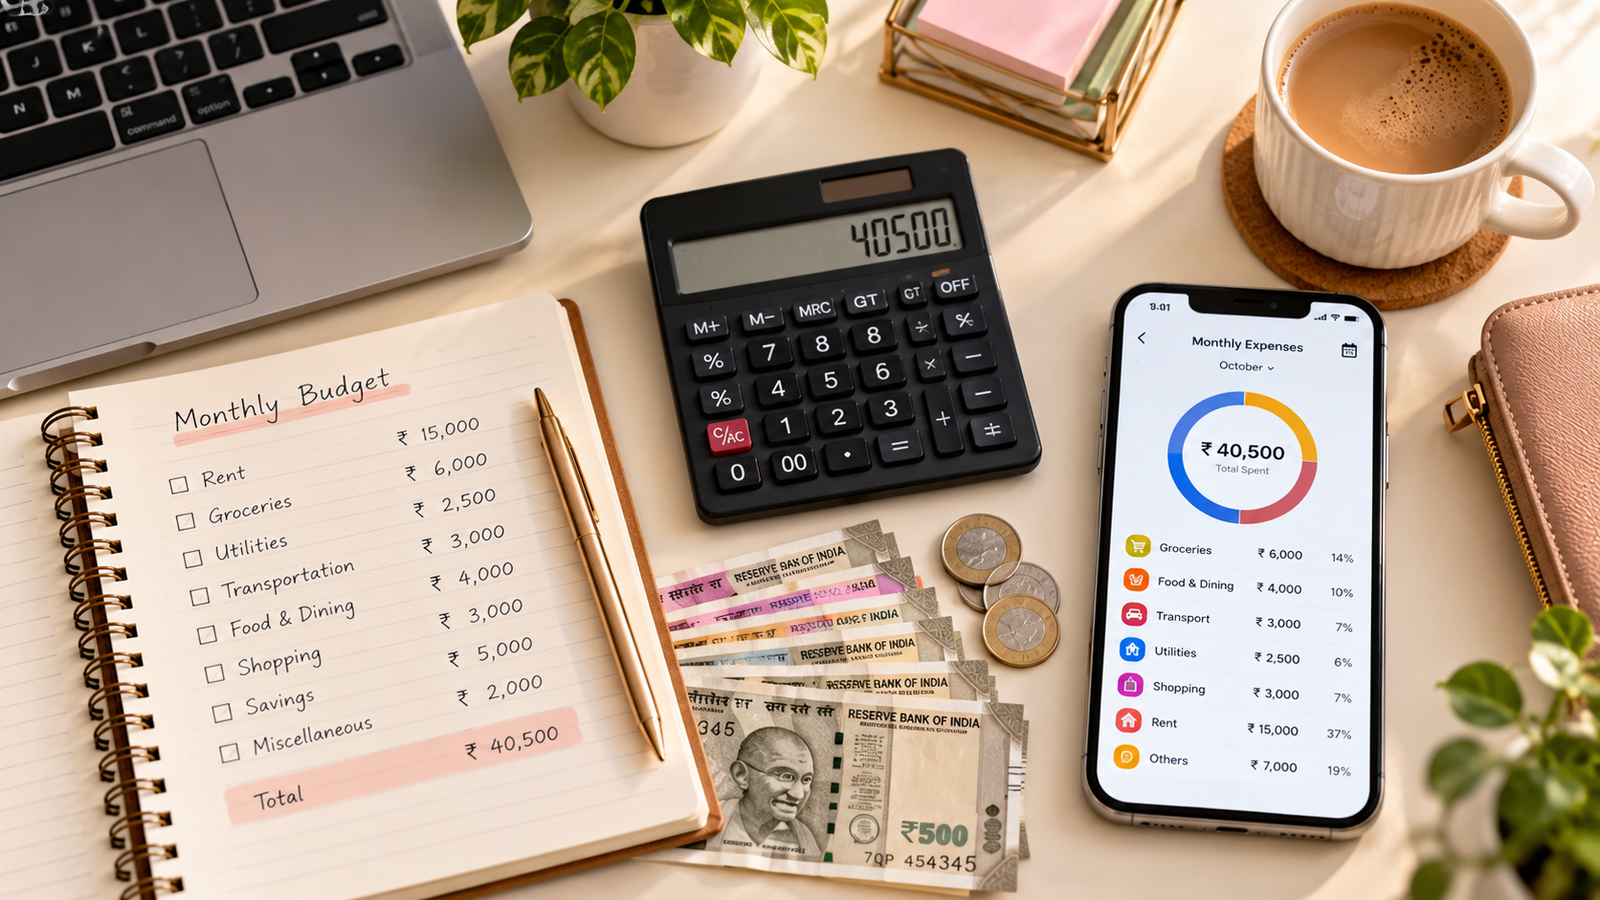
Step 3: Create a Practical Budget
Consider this illustrative monthly budget for someone earning ₹25,000:
Category | Monthly amount |
|---|---|
Housing and utilities | ₹8,000 |
Groceries | ₹5,000 |
Transportation | ₹2,500 |
Phone and internet | ₹1,000 |
Personal expenses | ₹3,000 |
Savings | ₹3,000 |
Emergency and miscellaneous | ₹2,500 |
Total | ₹25,000 |
This is only an example. Actual spending needs vary significantly by household, city, and financial obligations.
Step 4: Identify Unnecessary Spending
Review recurring subscriptions, frequent food deliveries, impulse purchases, and unused memberships.
Focus on expenses you can reduce without compromising essential needs.
Step 5: Build an Emergency Fund
Set aside money for unexpected expenses.
Begin with a manageable savings goal and gradually increase it based on your circumstances.
Step 6: Automate Savings
If possible, arrange a recurring transfer to a separate savings account after receiving your salary.
Choose an amount that does not interfere with essential bills or debt obligations.
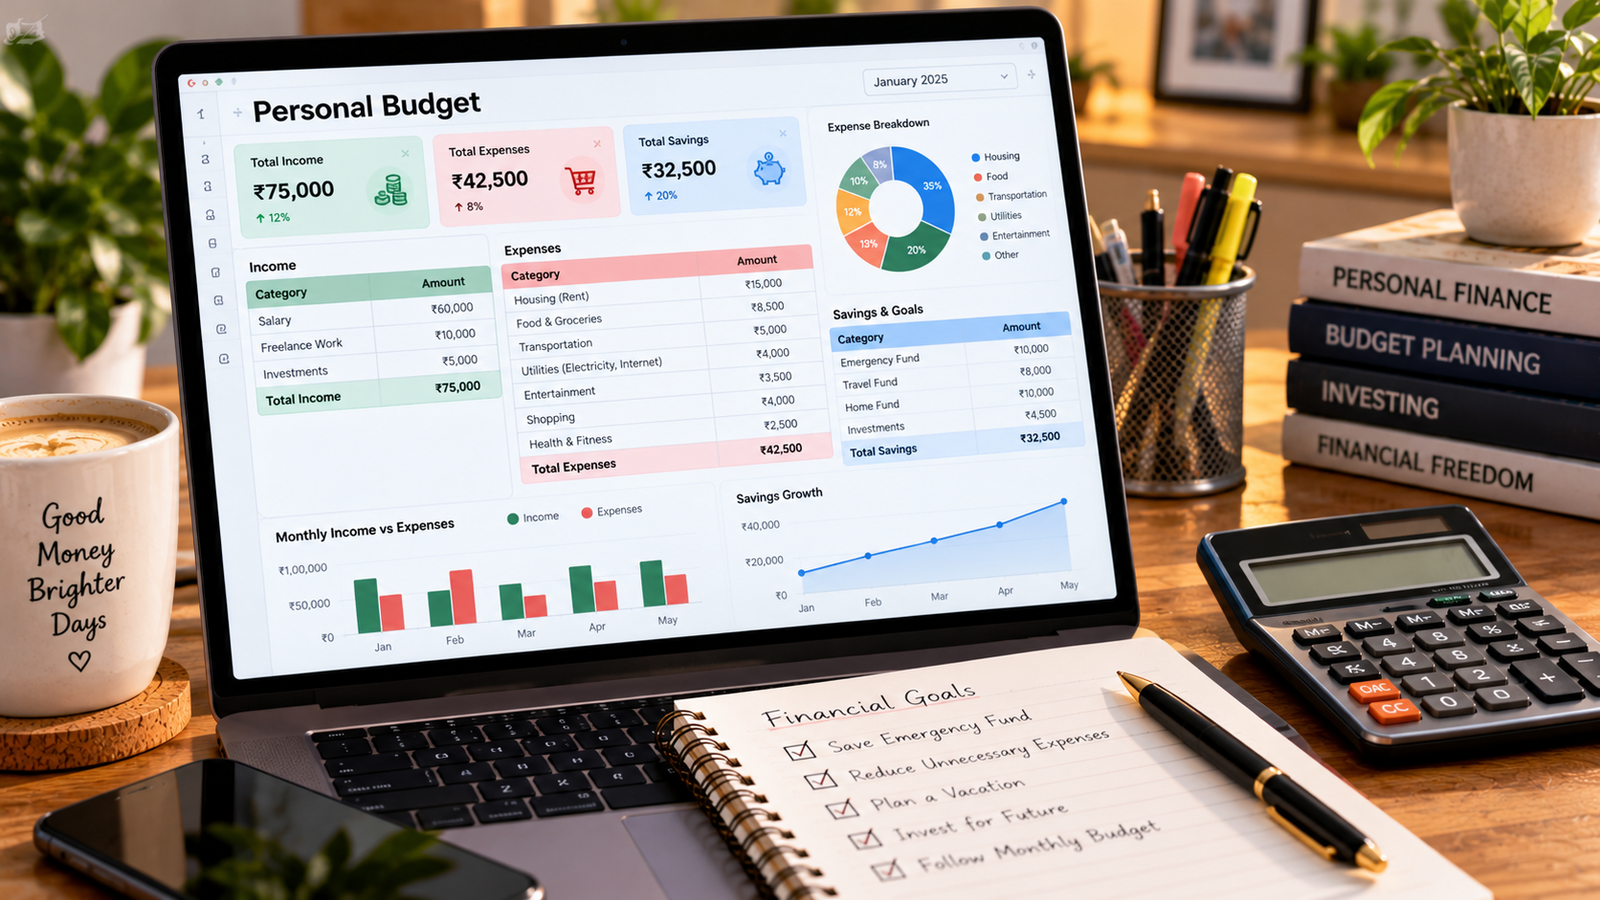
Step 7: Review Your Budget Monthly
Compare your planned expenses with actual spending.
Adjust categories when necessary instead of treating every unexpected expense as a failure.
Conclusion
Saving money on a low salary requires realistic budgeting and consistent habits. Start with an affordable amount, prioritize financial stability, and increase savings when your circumstances improve.